
 Yes Bank
YES BANK Max Credit Card Review 2026: Benefits, Fees & Rewards
Verified Official Data • Last updated November 2026
YES BANK Max Credit Card Net Value Calculator
Drag sliders to estimate YES BANK Max Credit Card's real annual net returns based on your actual spending habits.
Your Monthly Spend
₹50,000/moE-Commerce & Online
Daily Essentials
Most cards earn ₹0 rewards on fuel (surcharge waiver only).
Frequently excluded from rewards in India.
Lifestyle, Bills & Other
Almost always earns ₹0 and may carry a fee.
Often excluded or capped.
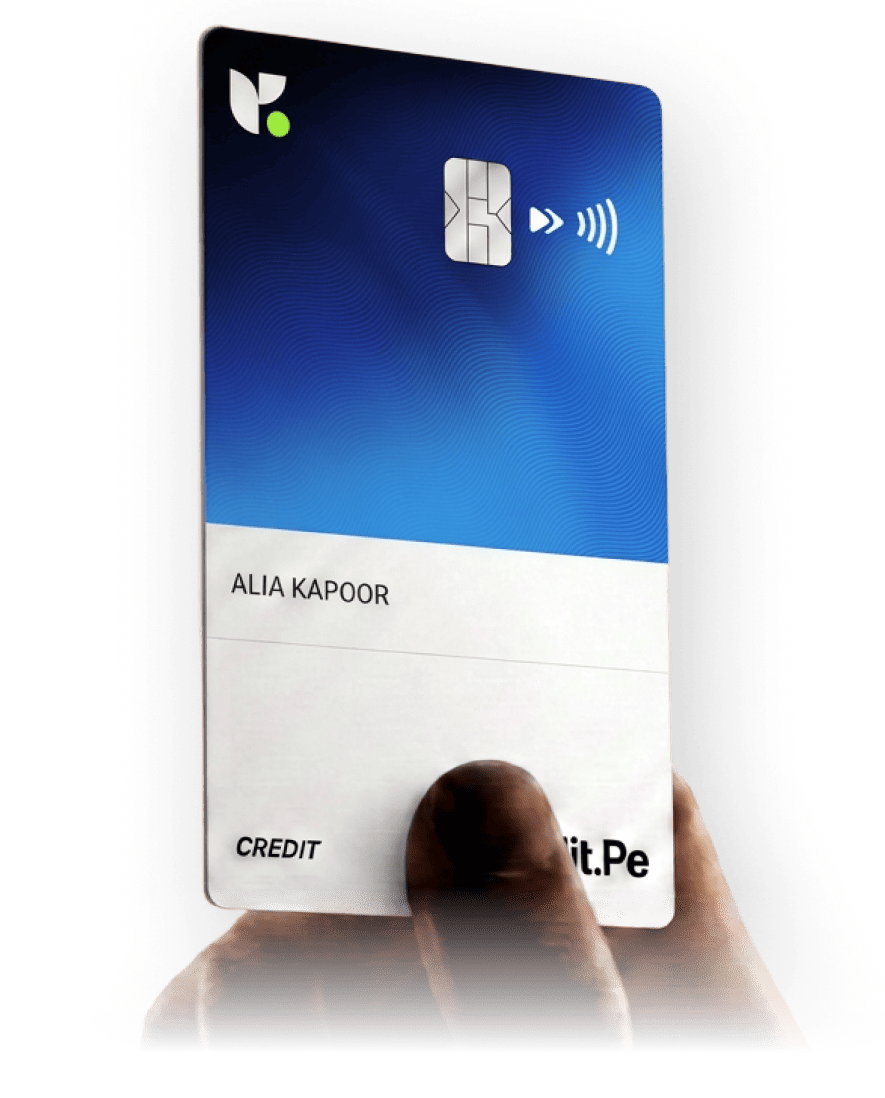
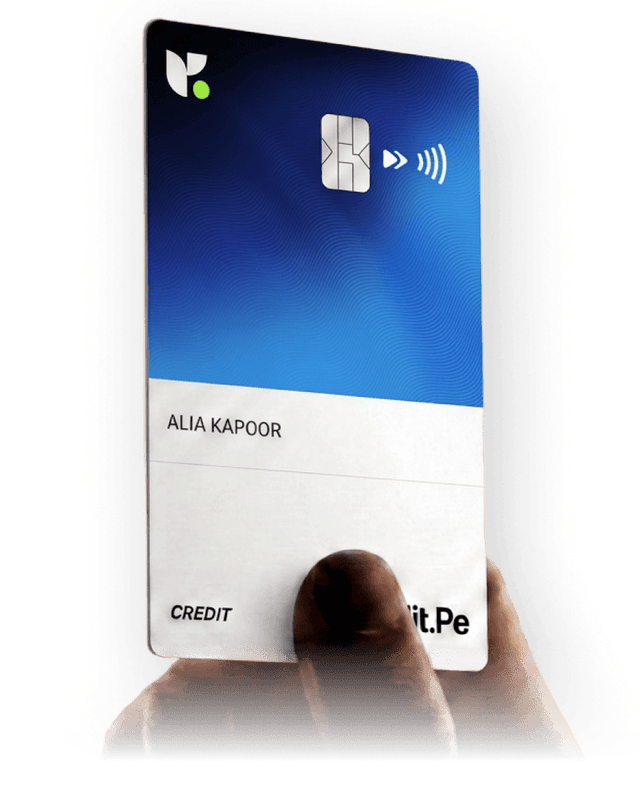
YES BANK Max Credit Card
Annual fee: ₹0
Savings & Milestones Tracker
1.53%
Value Yield (Net / Spent)
₹9,180
Annual Net Value
Eligibility at a glance
Yes Bank publishes no income figure for this card; approval rests on credit score and internal policy.
More infoHow Your Spends Convert to Rewards
Live calculation breakdown for YES BANK Max Credit Card
| Spend Category | Monthly Spend | Reward Rate | Monthly Cap | Monthly Value | Annual Value | Status / Caps |
|---|---|---|---|---|---|---|
Fuel | ₹4,000/mo | 0% Cashback | No cap | ₹0 | ₹0/yr | Excluded |
Utilities & Bills | ₹4,000/mo | 0% Cashback | No cap | ₹0 | ₹0/yr | Excluded |
Rent | ₹10,000/mo | 0% Cashback | No cap | ₹0 | ₹0/yr | Excluded |
Insurance | ₹1,500/mo | 0% Cashback | No cap | ₹0 | ₹0/yr | Excluded |
Other Online Shopping | ₹6,000/mo | 5% Cashback | No cap | ₹300 | ₹3,600/yr | Active Earn |
Amazon Spends | ₹3,500/mo | 5% Cashback | No cap | ₹175 | ₹2,100/yr | Active Earn |
Flipkart Spends | ₹2,000/mo | 5% Cashback | No cap | ₹100 | ₹1,200/yr | Active Earn |
Dining & Food Delivery | ₹5,000/mo | 1% Cashback | No cap | ₹50 | ₹600/yr | Active Earn |
Groceries | ₹7,000/mo | 1% Cashback | No cap | ₹70 | ₹840/yr | Active Earn |
Travel (Flights/Hotels) | ₹4,000/mo | 1% Cashback | No cap | ₹40 | ₹480/yr | Active Earn |
Other / Offline | ₹3,000/mo | 1% Cashback | No cap | ₹30 | ₹360/yr | Active Earn |
All ₹ values exclude GST. Perks like lounge access are shown separately and not added into net value. Rewards use your selected redemption mode (cashback / statement credit).
Is YES BANK Max Credit Card actually your best option?
YES BANK Max Credit Card Fees & Key Specifications
Issuance fees, spend waiver thresholds, forex markup, and complimentary airport lounge access.
Free
Zero feeLifetime Free
Zero ongoing feesNo Waiver
Lifetime free card3.5%
Cross-currency markupNone
No domestic accessNone
No international accessYES BANK Max Credit Card Cashback Rates & Redemption
Verified earn rates, accelerated multipliers, point conversion valuation, and redemption policies for 2026.
Applies to all non-excluded offline, general retail, and miscellaneous spends.
Instant digital redemption (2/5 friction)
Not published (verify with issuer)
Accelerated Category Multipliers (1)
No monthly cap published for online spend on either the yes.bank.in product page or the kredit.pe co-brand site as of 2026-11-13.
Also excluded per the official MCC table (not modelled, no matching SpendCategory): Stored Value Card/Wallets (6540,6541), Government/Gambling/Betting/Lotteries (7800,7801,7802,7995,9211,9222,9311,9399,9402,9405), Securities/Brokers (6211), Educational Services (8211,8220,8241,8244,8249,8299), Railways (4011,4111,4112), Tolls & bridges (4784), Marketing and Advertising services (7311), Financial Institutions (6010,6011,6012,6051,7322), Wire Transfer (4829), Agriculture (0820-0825,0763,0780,5261), Contract Services (1520,1711,1731,1740,1750,1761,1771,1799). UPI spend is reverse-tiered: 3% up to Rs.20,000/month, 5% above (kredit.pe FAQ) - not separately modelled, see baseRate note. Welcome bonus: kredit.pe markets a one-time 'Rs.1,000 cashback welcome bonus' for linking the card to Kredit.Pe UPI, but no spend threshold or T&C detail is published beyond the marketing page, so it is not encoded as a milestone (milestones left empty) to avoid fabricating an annualSpend figure.
YES BANK Max Credit Card Milestones & Perks
Welcome bonuses, annual renewal rewards, milestone spend targets, and exclusive lifestyle memberships.
Complimentary Lifestyle & Travel Privileges (3)
UPI-linked card, applied for via the Kredit.Pe app (co-brand fintech partner, WTEX Fintech Private Limited)
Existing YES BANK Credit Cardholders are not eligible for this card (official page disclosure)
Kredit.Pe markets a one-time Rs.1,000 cashback welcome bonus for linking the card to Kredit.Pe UPI, and 20% off flight vouchers redeemable in the Kredit.Pe app (not independently verified against a bank MITC, not counted in valuation)
YES BANK Max Credit Card Eligibility & Data Sources
Applicant eligibility criteria, devaluation tracking history, and verified source citations.
Not published by Yes Bank
rupay
This card's data has been audited directly against official Yes Bank Key Fact Statements (KFS) and published schedule of charges. Point valuations include real redemption friction factors to compute true net financial value.
YES BANK Max Credit Card Specification Sheet
Comprehensive rules, fees, and parameters verified directly against issuer details.
| Feature | YES BANK Max Credit CardYes Bank |
|---|---|
| Joining fee | Nil |
| Annual fee | Lifetime free |
| Fee waiver | — |
| Base reward | 1% cashback |
| Top reward categories | 5% online |
| Redemption friction | Easy |
| Point expiry | Not published |
| Lounge access | None |
| Forex markup | 3.5% |
| Fuel surcharge | None |
| Min income · salaried | Not stated |
| Min income · self-employed | Not stated |
| Eligibility (as stated) | Not published by bank |
| Recent devaluations | None recorded |
| Verified against |
YES BANK Max Credit Card Review & Spending Guide (2026)
The YES BANK Max Credit Card by Yes Bank is a prominent credit card in the Indian market, categorized under the entry tier. Offering a base rewards engine of 1% cashback, this card targets users looking to optimize their personal finances.
When evaluating the real-world value of the YES BANK Max Credit Card, it's essential to look beyond the joining fee of ₹0 and annual fee of ₹0. With our real-time calculator above, you can map out your monthly category spends (online shopping, dining, travel, utilities, groceries, etc.) to see if you can trigger the spend-based annual fee waiver of N/A, which determines your true Net Annual Value (NTV).
Rewards Potential & Category Multipliers
For accelerated spenders, the YES BANK Max Credit Card features key reward multipliers:
- 5% online (uncapped).
- Exclusions: No rewards are earned on fuel, insurance, rent, utilities categories.
Lounge Access & Extra Perks
Perks add immense value that calculations often leave out. The YES BANK Max Credit Card offers:
- Domestic Lounges: No domestic lounge visits available.
- International Lounges: No international lounge visits available.
Points Redemption and Point Expiry
Earning points is only half the battle. Redemptions are subject to a friction index of 2/5 (representing Instant digital redemption (2/5 friction)). Points are valid for an unpublished period (verify with issuer).
Who the YES BANK Max Credit Card benefits the most
Derived from this card's actual earn rates, caps and perks — not a generic profile.
- People whose spending is concentrated in online shopping — the card's strongest rate at 5% cashback, with no monthly cap stated. No monthly cap published for online spend on either the yes.bank.in product page or the kredit.pe co-brand site as of 2026-11-13.
- Anyone who refuses to pay for a card. With a ₹0 annual fee and ₹0 joining fee, there is no break-even to chase — every rupee of reward is profit.
- People who never get around to redeeming. Redemption friction here is 2/5, so rewards convert with little effort instead of rotting in a points balance.
Who should avoid the YES BANK Max Credit Card
The cases where this card quietly costs more than it pays back.
- Anyone whose spending is heavy on fuel, insurance premiums, rent payments, utility bills and recharges. These categories earn absolutely nothing on this card — not a reduced rate, zero. Also excluded per the official MCC table (not modelled, no matching SpendCategory): Stored Value Card/Wallets (6540,6541), Government/Gambling/Betting/Lotteries (7800,7801,7802,7995,9211,9222,9311,9399,9402,9405), Securities/Brokers (6211), Educational Services (8211,8220,8241,8244,8249,8299), Railways (4011,4111,4112), Tolls & bridges (4784), Marketing and Advertising services (7311), Financial Institutions (6010,6011,6012,6051,7322), Wire Transfer (4829), Agriculture (0820-0825,0763,0780,5261), Contract Services (1520,1711,1731,1740,1750,1761,1771,1799). UPI spend is reverse-tiered: 3% up to Rs.20,000/month, 5% above (kredit.pe FAQ) - not separately modelled, see baseRate note. Welcome bonus: kredit.pe markets a one-time 'Rs.1,000 cashback welcome bonus' for linking the card to Kredit.Pe UPI, but no spend threshold or T&C detail is published beyond the marketing page, so it is not encoded as a milestone (milestones left empty) to avoid fabricating an annualSpend figure.
- Travellers and overseas online shoppers. The 3.5% forex markup plus 18% GST on that markup works out to about 4.13% on every foreign-currency transaction — usually more than the rewards you earn on it.
- Frequent flyers looking for airport comfort. This card carries no complimentary lounge access.
- Anyone who revolves a balance. Credit card interest in India typically runs 36–45% a year plus 18% GST on the interest — that erases every reward this card can pay, on any spending pattern.
Tax implications of the YES BANK Max Credit Card
Indian tax treatment of the fees, rewards and foreign spends on this specific card.
GST on fees and charges. This card has no joining or annual fee, so there is no GST on fees to pay. GST at 18% still applies to any interest, late payment fee, cash advance fee, EMI processing fee and the forex markup you incur.
Are the reward points taxable? Points or cashback earned in proportion to your own spending are treated as a post-purchase discount rather than income, so a salaried individual does not pay tax on them. The cashback on this card reduces the cost of what you bought; it is not "other income" in your ITR. Two exceptions matter: benefits received from a business relationship (not from your own spending) can attract TDS at 10% under section 194R where the value exceeds ₹20,000 in a year, and a gift or voucher received from the bank with no link to your spending can be taxable under section 56(2)(x) if total gifts from non-relatives cross ₹50,000 in a year.
Is the annual fee deductible? There is no annual fee on this card, so the question does not arise. Any GST-bearing charges you do incur follow the same rule below.
Foreign spends, TCS and the LRS. The 3.5% markup attracts 18% GST, making it about 4.13% effectively. TCS under the Liberalised Remittance Scheme runs at 20% above ₹10 lakh of remittances in a financial year; international credit card spends have so far been kept outside the LRS pending notification, so no TCS is deducted at the till today. Where TCS is collected on any remittance, it is not a sunk cost — it is creditable against your tax liability and refundable through your ITR.
Spends the tax department can see. Aggregate credit card payments of ₹10 lakh or more in a financial year (₹1 lakh or more if paid in cash) are reported by Yes Bank in the Statement of Financial Transactions and show up in your AIS. That is not a tax by itself, but the spending should be consistent with the income you declare.
Eligibility and documents for the YES BANK Max Credit Card
Yes Bank does not publish a numeric income requirement for this entry-tier card.
Eligibility
- Income: Yes Bank does not publish a figure for this card. Expect the usual entry-level threshold of roughly ₹20,000–₹30,000 a month, confirmed at application.
- Age: typically 21 to 60 for salaried applicants and up to 65 for self-employed; add-on cards from 18.
- Credit score: a CIBIL score of 750+ materially improves approval odds on any card, including this one.
- Residency: resident Indian with a verifiable address in a city Yes Bank services.
Documents required
- Identity: PAN card (mandatory) plus Aadhaar, passport, voter ID or driving licence.
- Address: Aadhaar, passport, utility bill or registered rent agreement.
- Income (salaried): last 3 months' salary slips and 3–6 months' bank statements showing salary credit; Form 16 for the latest year.
- Income (self-employed): latest 1–2 years' ITR with computation, audited financials where applicable, and 6 months' current account statements.
- Photograph: one recent passport-size photo (often skipped in a full digital journey).
- Existing Yes Bank customers with a salary or pre-approved relationship usually skip the income documents entirely.
Nomination note: a credit card has no nominee — nomination applies to deposits and investments. What matters here is that your family knows the card exists and knows the outstanding, so it can be settled from the estate promptly instead of accruing interest and late fees after the fact.
How to apply for the YES BANK Max Credit Card
- Check for a pre-approved offer first. Log in to Yes Bank net banking or the mobile app. A pre-approved journey skips income documents and, more importantly, avoids a hard enquiry on your credit report if you are declined.
- Confirm the current fee and rates on the official page before applying — banks revise these without much notice.
- Apply online with PAN, Aadhaar and employment details, or walk into a Yes Bank branch if your income profile needs manual assessment.
- Complete KYC. Most issuers now offer video KYC that finishes in minutes; physical verification adds a few days.
- Confirm the credit limit before activating. The limit determines how much of your spending you can actually route here, which is what the reward maths above assumes.
- Set a full-payment auto-debit on the due date the day the card arrives. Interest of 36–45% a year plus GST is the single fastest way to turn this card into a loss.
YES BANK Max Credit Card — frequently asked questions
Answers use this card's own numbers, verified November 2026.
What are the main benefits of the YES BANK Max Credit Card?
The short version: its strongest return is on online shopping at 5% cashback. And it costs nothing to hold — no joining fee, no annual fee. The sections below put numbers and conditions on each of these.
Is the YES BANK Max Credit Card lifetime free?
Yes. There is no joining fee and no annual fee, and Yes Bank attaches no spend condition to keeping it free — the card stays ₹0 for as long as you hold it. "Free" covers the fee only: interest on revolving balances and the late-payment or over-limit charges in the issuer's MITC still apply if you run into them.
What is the annual fee for the YES BANK Max Credit Card, and can it be waived?
The YES BANK Max Credit Card has no annual fee and no joining fee. There is nothing to waive and no break-even spend to worry about.
What charges apply on the YES BANK Max Credit Card?
The recurring schedule: no joining fee and no annual fee. Foreign currency spends carry a 3.5% forex markup plus GST on it. There is no fuel surcharge waiver. Interest applies only if you revolve a balance, and late-payment or over-limit fees sit in the issuer's MITC — pay in full each month and none of those touch you.
How much do you actually earn on the YES BANK Max Credit Card?
The base rate is 1% cashback. The accelerated categories are online shopping at 5% cashback.
Which spends earn no rewards on the YES BANK Max Credit Card?
fuel, insurance premiums, rent payments, utility bills and recharges earn zero. Also excluded per the official MCC table (not modelled, no matching SpendCategory): Stored Value Card/Wallets (6540,6541), Government/Gambling/Betting/Lotteries (7800,7801,7802,7995,9211,9222,9311,9399,9402,9405), Securities/Brokers (6211), Educational Services (8211,8220,8241,8244,8249,8299), Railways (4011,4111,4112), Tolls & bridges (4784), Marketing and Advertising services (7311), Financial Institutions (6010,6011,6012,6051,7322), Wire Transfer (4829), Agriculture (0820-0825,0763,0780,5261), Contract Services (1520,1711,1731,1740,1750,1761,1771,1799). UPI spend is reverse-tiered: 3% up to Rs.20,000/month, 5% above (kredit.pe FAQ) - not separately modelled, see baseRate note. Welcome bonus: kredit.pe markets a one-time 'Rs.1,000 cashback welcome bonus' for linking the card to Kredit.Pe UPI, but no spend threshold or T&C detail is published beyond the marketing page, so it is not encoded as a milestone (milestones left empty) to avoid fabricating an annualSpend figure. If those categories are a big share of your monthly outgo, your effective return will be well below the advertised rate.
Does the YES BANK Max Credit Card offer airport lounge access?
No. This card carries no complimentary lounge visits. If lounge access matters to you, look at a card that states a visit count in writing.
What does the YES BANK Max Credit Card charge on foreign currency spends?
A 3.5% markup, plus 18% GST on that markup, so about 4.13% effectively. On a ₹1 lakh foreign spend that is roughly ₹4,130.
Do reward points on the YES BANK Max Credit Card expire?
The issuer has not published a verified expiry for these rewards. Check the current wallet terms before relying on a long redemption period.
Who is eligible for the YES BANK Max Credit Card?
Yes Bank does not publish a minimum income or fixed eligibility score for this card. In practice approval rests on your credit score, repayment history, existing relationship with Yes Bank and its internal policy, which the bank confirms only during the application. No published floor means no one — including us — can promise approval, and a strong credit score matters more than any single number.
Is the YES BANK Max Credit Card annual fee tax-deductible, and are reward points taxable?
For a salaried cardholder the fee is a personal expense and is not deductible. If the card is used genuinely for business or professional spends, the fee and GST can be claimed as a business expense (and the GST as input credit where the card is billed to a GST-registered entity). Reward points earned in proportion to your own spending are generally treated as a post-purchase discount, not income, so they are not taxed in your hands.
Is TCS applicable on YES BANK Max Credit Card spends abroad?
Tax Collected at Source under the Liberalised Remittance Scheme applies at 20% above the ₹10 lakh annual threshold for remittances and forex card loads. International spends on Indian credit cards have so far been kept outside the LRS pending notification, so no TCS is deducted at the point of sale today. This has been changed and deferred more than once — confirm the current position with Yes Bank before a large overseas spend. Any TCS actually collected is not a cost: it is creditable against your income tax liability and refundable when you file your ITR.
What happens to the YES BANK Max Credit Card account after the cardholder's death?
A credit card is an unsecured personal liability and cannot be inherited or transferred — the card must be surrendered and closed. Inform Yes Bank in writing with the death certificate; the outstanding balance becomes payable from the deceased's estate, and the legal heirs are liable only to the extent of the assets they inherit, not personally. Any add-on cards stop working immediately. Unredeemed reward points are normally forfeited on closure, so a family member holding a large balance should redeem while the account is active. Nomination applies to deposits and investments, not to credit cards — but if there is a fixed deposit backing a secured card, the nomination on that FD governs its release.
Similar & Alternative Cards
Explore other top-rated Entry-level credit cards in India
Amazon Pay ICICI Bank Credit Card
ICICI Platinum Chip Credit Card
ICICI Bank Parakram Credit Card
Google Pay Flex Axis Bank Credit Card
IndianOil Easy Axis Bank Credit Card

Fibe Axis Bank Credit Card
Related Guides & Tools
Ranked card lists YES BANK Max Credit Card appears in, plus calculators for card debt decisions