
 Indian Overseas Bank
IOB novio Platinum Credit Card
Verified Official Data • 2026-08
Nil
Lifetime Free
None
3.5%
Most cards earn ₹0 rewards on fuel (surcharge waiver only).
Frequently excluded from rewards in India.
Spends-to-Rewards Breakdown
Live conversion of your active monthly spends
Yield & Milestone Tracker
0.00%
Is IOB novio Platinum Credit Card really your best option?
Run your spend profile against all 532 cards in India and see where this one ranks.
Key Specifications
Nil
Lifetime Free
None
3.5%
Rewards Structure (2026)
Official earn rates, accelerated multipliers and category caps
All non-excluded general spends
Lounge & Travel Perks
None
None
Redemption & Expiry
Reward structure not disclosed on official IOB MITC; marketing site references 'novioCoin' rewards redeemable at partner brands
Exclusion Honesty: This data has been verified against official Indian Overseas Bank publications. Exclusions and point friction factors are encoded in full to ensure truthful net calculations.
Official Specification Sheet
Verified parameters formatted for mobile reading without horizontal scrolling
IOB novio Platinum Credit Card Review & Guide (2026)
The IOB novio Platinum Credit Card by Indian Overseas Bank operates on a base reward rate of 0 reward points per ₹100 in the entry tier.
Evaluating this card requires looking past the ₹0 joining fee and ₹0 annual fee to assess your real Net Annual Value (NTV). With the live calculator above, verify if your spend meets fee waivers or accelerates rewards in top merchant categories.
Who Benefits Most
- People who want one flat, no-thinking rate: every eligible spend earns 0 points per ₹100 (about 0.00% in value at best redemption), with no category tracking.
- Anyone who refuses to pay for a card: with a ₹0 annual fee, there is no break-even to chase.
Who Should Avoid
- Frequent overseas shoppers: 3.5% forex markup + 18% GST on markup (~4.13%) eats into rewards.
- Anyone revolving balances: credit card interest in India runs 36–45% + 18% GST, erasing all rewards.
Hidden Charges & Fine Print
Forex markup is effectively 4.13%
18% GST applies to the 3.5% markup. Always decline Dynamic Currency Conversion (billing in INR) abroad.
Standard MITC fees
Cash withdrawal fee (2.5% min ₹500), over-limit charges, late payment charges, rent/wallet fee.
Tax Implications
GST on Fees: All quoted fees exclude 18% GST. The ₹0 joining fee bills as ₹0 and renewal as ₹0.
Reward Points Taxability: Points earned from personal spending are considered discounts and are not taxed. Business rewards may attract TDS under Section 194R if gifts exceed ₹20,000/year.
LRS & TCS: International spends on Indian cards are currently exempted from 20% LRS TCS pending central notification.
Eligibility & Documentation
- Age 21–60 (salaried) or up to 65 (self-employed).
- CIBIL score 750+ recommended.
- Income: As assessed by bank.
- PAN card + Aadhaar/Passport.
- Last 3 months salary slips / Form 16 / ITR.
How to Apply
- Check for pre-approved offers in net banking to skip documentation.
- Confirm latest fees and exclusions on the official page.
- Apply online with PAN and Aadhaar for video KYC.
- Set full auto-debit on the due date immediately upon receipt.
IOB novio Platinum Credit Card — FAQs
Verified official answers • Updated 2026-08
IOB novio Platinum Credit Card is Lifetime Free with no annual fee.
Similar Cards to Consider
Alternative cards in the entry tier and Indian Overseas Bank portfolio
Indian Overseas BankIOB novio Platinum Credit Card
Verified Official Data • Last updated 2026-08
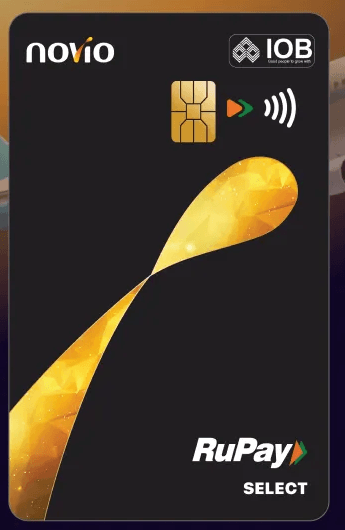
Net Value Calculator
Drag sliders to estimate this card's annual value based on your actual spending habits.
Your Monthly Spend
₹50,000/moE-Commerce & Online
Daily Essentials
Most cards earn ₹0 rewards on fuel (surcharge waiver only).
Frequently excluded from rewards in India.
Lifestyle, Bills & Other
Almost always earns ₹0 and may carry a fee.
Often excluded or capped.
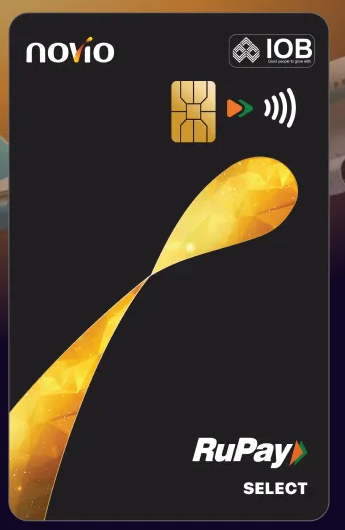
Savings & Milestones Tracker
0.00%
Value Yield (Net / Spent)
₹0
Annual Net Value
How Your Spends Convert to Rewards
Live calculation breakdown for IOB novio Platinum Credit Card
| Spend Category | Monthly Spend | Reward Rate | Points Earned | Monthly Value | Annual Value | Status / Caps |
|---|---|---|---|---|---|---|
Other Online Shopping | ₹6,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Amazon Spends | ₹3,500/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Flipkart Spends | ₹2,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Dining & Food Delivery | ₹5,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Groceries | ₹7,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Fuel | ₹4,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Utilities & Bills | ₹4,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Travel (Flights/Hotels) | ₹4,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Rent | ₹10,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Insurance | ₹1,500/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
Other / Offline | ₹3,000/mo | 0 Pts / ₹100 | 0 pts0 pts/yr | ₹0 | ₹0/yr | Active Earn |
All ₹ values exclude GST. Perks like lounge access are shown separately and not added into net value. Rewards use your selected redemption mode (cashback / statement credit).
Is IOB novio Platinum Credit Card actually your best option?
Run the same spend against all 532 cards and see where this one ranks.
Key Specifications & Core Privileges
Issuance fees, spend waiver thresholds, forex markup, and complimentary airport lounge access.
Free
Zero feeLifetime Free
Zero ongoing feesNo Waiver
Lifetime free card3.5%
Cross-currency markupNone
No domestic accessNone
No international accessRewards Structure & Redemption
Verified earn rates, accelerated multipliers, point conversion valuation, and redemption policies for 2026.
Applies to all non-excluded offline, general retail, and miscellaneous spends.
Moderate/Portal redemption (3/5 friction)
Points never expire
Flat Reward Structure: This card does not rely on fragmented category multipliers or rotating merchant caps. All eligible retail purchases earn rewards at the flat base rate, giving you predictable returns.
Privileges, Milestones & Card Perks
Welcome bonuses, annual renewal rewards, milestone spend targets, and exclusive lifestyle memberships.
Complimentary Lifestyle & Travel Privileges (3)
FD-secured: free physical card requires cumulative FD amount >= Rs.10,000 (official MITC card-variants table)
Credit limit enhanced by opening additional Fixed Deposits from the novio app
Card Cancellation Fee Rs.499+GST if cancelled within 1 year
Eligibility, Governance & Data Verification
Applicant eligibility criteria, devaluation tracking history, and verified source citations.
Standard bank credit criteria applies
rupay
This card's data has been audited directly against official Indian Overseas Bank Key Fact Statements (KFS) and published schedule of charges. Point valuations include real redemption friction factors to compute true net financial value.
Official Specification Sheet
Comprehensive rules, fees, and parameters verified directly against issuer details.
| Feature | IOB novio Platinum Credit CardIndian Overseas Bank |
|---|---|
| Joining fee | Nil |
| Annual fee | Lifetime free |
| Fee waiver | — |
| Base reward | 0 pts / ₹100 |
| Top reward categories | Base rate only |
| Redemption friction | Moderate |
| Point expiry | Never expire |
| Lounge access | None |
| Forex markup | 3.5% |
| Fuel surcharge | None |
| Min income · salaried | Not stated |
| Min income · self-employed | Not stated |
| Eligibility (as stated) | Not stated |
| Recent devaluations | None recorded |
| Verified against |
Detailed IOB novio Platinum Credit Card Credit Card Review & Spends Guide (2026)
The IOB novio Platinum Credit Card by Indian Overseas Bank is a prominent credit card in the Indian market, categorized under the entry tier. Offering a base rewards engine of 0 reward points per ₹100, this card targets users looking to optimize their personal finances.
When evaluating the real-world value of the IOB novio Platinum Credit Card, it's essential to look beyond the joining fee of ₹0 and annual fee of ₹0. With our real-time calculator above, you can map out your monthly category spends (online shopping, dining, travel, utilities, groceries, etc.) to see if you can trigger the spend-based annual fee waiver of N/A, which determines your true Net Annual Value (NTV).
Rewards Potential & Category Multipliers
For accelerated spenders, the IOB novio Platinum Credit Card features key reward multipliers:
Lounge Access & Extra Perks
Perks add immense value that calculations often leave out. The IOB novio Platinum Credit Card offers:
- Domestic Lounges: No domestic lounge visits available.
- International Lounges: No international lounge visits available.
Points Redemption and Point Expiry
Earning points is only half the battle. Redemptions are subject to a friction index of 3/5 (representing Moderate/Portal redemption (3/5 friction)). Note: Reward structure not disclosed on official IOB MITC; marketing site references 'novioCoin' rewards redeemable at partner brands. Points are valid for a lifetime (no expiry).
Who the IOB novio Platinum Credit Card benefits the most
Derived from this card's actual earn rates, caps and perks — not a generic profile.
- People who want one flat, no-thinking rate: every eligible spend earns 0 points per ₹100 (about 0.00% in value at the best redemption), with no category tracking to do.
- Anyone who refuses to pay for a card. With a ₹0 annual fee and ₹0 joining fee, there is no break-even to chase — every rupee of reward is profit.
Who should avoid the IOB novio Platinum Credit Card
The cases where this card quietly costs more than it pays back.
- Travellers and overseas online shoppers. The 3.5% forex markup plus 18% GST on that markup works out to about 4.13% on every foreign-currency transaction — usually more than the rewards you earn on it.
- Frequent flyers looking for airport comfort. This card carries no complimentary lounge access.
- Anyone reading the headline points rate literally. Each point is worth only ₹0, so "0 points per ₹100" is really about 0.00% back in value.
- Anyone who revolves a balance. Credit card interest in India typically runs 36–45% a year plus 18% GST on the interest — that erases every reward this card can pay, on any spending pattern.
Hidden charges and fine print on the IOB novio Platinum Credit Card
The costs that sit below the marketing page, verified against Indian Overseas Bank disclosures dated 2026-08.
Forex markup of 3.5% is really 4.13%
GST at 18% applies to the markup, so 3.5% becomes about 4.13% in real terms. Also decline Dynamic Currency Conversion at foreign terminals: paying "in INR" adds another 3–5% on top of this.
Redemption fine print
Reward structure not disclosed on official IOB MITC; marketing site references 'novioCoin' rewards redeemable at partner brands Redemption fees and minimum-balance thresholds are the most commonly missed cost on Indian cards — factor them in before comparing headline earn rates.
No fuel surcharge waiver
This card carries no fuel surcharge waiver in the published terms, so the usual ~1% surcharge levied by petrol pumps stays on your bill.
Charges every Indian card carries
Cash withdrawal fees (typically 2.5% of the amount, minimum ₹500) with interest from day one and no interest-free period, late payment fees graded by outstanding balance, over-limit charges, EMI conversion processing fees and interest, rent-payment and wallet-load fees, and payment-return charges. These are listed in the bank's MITC document, not in the marketing page — read it once before you apply.
Tax implications of the IOB novio Platinum Credit Card
Indian tax treatment of the fees, rewards and foreign spends on this specific card.
GST on fees and charges. This card has no joining or annual fee, so there is no GST on fees to pay. GST at 18% still applies to any interest, late payment fee, cash advance fee, EMI processing fee and the forex markup you incur.
Are the reward points taxable? Points or cashback earned in proportion to your own spending are treated as a post-purchase discount rather than income, so a salaried individual does not pay tax on them. The same applies to the points here, valued at ₹0 per point on redemption. Two exceptions matter: benefits received from a business relationship (not from your own spending) can attract TDS at 10% under section 194R where the value exceeds ₹20,000 in a year, and a gift or voucher received from the bank with no link to your spending can be taxable under section 56(2)(x) if total gifts from non-relatives cross ₹50,000 in a year.
Is the annual fee deductible? There is no annual fee on this card, so the question does not arise. Any GST-bearing charges you do incur follow the same rule below.
Foreign spends, TCS and the LRS. The 3.5% markup attracts 18% GST, making it about 4.13% effectively. TCS under the Liberalised Remittance Scheme runs at 20% above ₹10 lakh of remittances in a financial year; international credit card spends have so far been kept outside the LRS pending notification, so no TCS is deducted at the till today. Where TCS is collected on any remittance, it is not a sunk cost — it is creditable against your tax liability and refundable through your ITR.
Spends the tax department can see. Aggregate credit card payments of ₹10 lakh or more in a financial year (₹1 lakh or more if paid in cash) are reported by Indian Overseas Bank in the Statement of Financial Transactions and show up in your AIS. That is not a tax by itself, but the spending should be consistent with the income you declare.
Eligibility and documents for the IOB novio Platinum Credit Card
Indian Overseas Bank does not publish a numeric income requirement for this entry-tier card.
Eligibility
- Income: Indian Overseas Bank does not publish a figure for this card. Expect the usual entry-level threshold of roughly ₹20,000–₹30,000 a month, confirmed at application.
- Age: typically 21 to 60 for salaried applicants and up to 65 for self-employed; add-on cards from 18.
- Credit score: a CIBIL score of 750+ materially improves approval odds on any card, including this one.
- Residency: resident Indian with a verifiable address in a city Indian Overseas Bank services.
Documents required
- Identity: PAN card (mandatory) plus Aadhaar, passport, voter ID or driving licence.
- Address: Aadhaar, passport, utility bill or registered rent agreement.
- Income (salaried): last 3 months' salary slips and 3–6 months' bank statements showing salary credit; Form 16 for the latest year.
- Income (self-employed): latest 1–2 years' ITR with computation, audited financials where applicable, and 6 months' current account statements.
- Photograph: one recent passport-size photo (often skipped in a full digital journey).
- Existing Indian Overseas Bank customers with a salary or pre-approved relationship usually skip the income documents entirely.
Nomination note: a credit card has no nominee — nomination applies to deposits and investments. What matters here is that your family knows the card exists and knows the outstanding, so it can be settled from the estate promptly instead of accruing interest and late fees after the fact.
How to apply for the IOB novio Platinum Credit Card
- Check for a pre-approved offer first. Log in to Indian Overseas Bank net banking or the mobile app. A pre-approved journey skips income documents and, more importantly, avoids a hard enquiry on your credit report if you are declined.
- Confirm the current fee and rates on the official page before applying — banks revise these without much notice.
- Apply online with PAN, Aadhaar and employment details, or walk into a Indian Overseas Bank branch if your income profile needs manual assessment.
- Complete KYC. Most issuers now offer video KYC that finishes in minutes; physical verification adds a few days.
- Confirm the credit limit before activating. The limit determines how much of your spending you can actually route here, which is what the reward maths above assumes.
- Set a full-payment auto-debit on the due date the day the card arrives. Interest of 36–45% a year plus GST is the single fastest way to turn this card into a loss.
IOB novio Platinum Credit Card — frequently asked questions
Answers use this card's own numbers, verified 2026-08.
What is the annual fee for the IOB novio Platinum Credit Card, and can it be waived?
The IOB novio Platinum Credit Card has no annual fee and no joining fee. There is nothing to waive and no break-even spend to worry about.
How much do you actually earn on the IOB novio Platinum Credit Card?
The base rate is 0 points per ₹100, and each point is worth ₹0 at the best redemption — roughly 0.00% in value. There are no accelerated categories — the rate is flat across eligible spends.
Does the IOB novio Platinum Credit Card offer airport lounge access?
No. This card carries no complimentary lounge visits. If lounge access matters to you, look at a card that states a visit count in writing.
What does the IOB novio Platinum Credit Card charge on foreign currency spends?
A 3.5% markup, plus 18% GST on that markup, so about 4.13% effectively. On a ₹1 lakh foreign spend that is roughly ₹4,130.
Do reward points on the IOB novio Platinum Credit Card expire?
No — points on this card do not carry a stated expiry. That does not protect you from devaluation, only from lapse.
Is the IOB novio Platinum Credit Card annual fee tax-deductible, and are reward points taxable?
For a salaried cardholder the fee is a personal expense and is not deductible. If the card is used genuinely for business or professional spends, the fee and GST can be claimed as a business expense (and the GST as input credit where the card is billed to a GST-registered entity). Reward points earned in proportion to your own spending are generally treated as a post-purchase discount, not income, so they are not taxed in your hands.
Is TCS applicable on IOB novio Platinum Credit Card spends abroad?
Tax Collected at Source under the Liberalised Remittance Scheme applies at 20% above the ₹10 lakh annual threshold for remittances and forex card loads. International spends on Indian credit cards have so far been kept outside the LRS pending notification, so no TCS is deducted at the point of sale today. This has been changed and deferred more than once — confirm the current position with Indian Overseas Bank before a large overseas spend. Any TCS actually collected is not a cost: it is creditable against your income tax liability and refundable when you file your ITR.
What happens to the IOB novio Platinum Credit Card account after the cardholder's death?
A credit card is an unsecured personal liability and cannot be inherited or transferred — the card must be surrendered and closed. Inform Indian Overseas Bank in writing with the death certificate; the outstanding balance becomes payable from the deceased's estate, and the legal heirs are liable only to the extent of the assets they inherit, not personally. Any add-on cards stop working immediately. Unredeemed reward points are normally forfeited on closure, so a family member holding a large balance should redeem while the account is active. Nomination applies to deposits and investments, not to credit cards — but if there is a fixed deposit backing a secured card, the nomination on that FD governs its release.
Similar & Alternative Cards
Explore other top-rated Entry-level credit cards in India
Amazon Pay ICICI Bank Credit Card
ICICI Platinum Chip Credit Card
ICICI Bank Parakram Credit Card
Google Pay Flex Axis Bank Credit Card
Axis Bank MY Zone Easy Credit Card
IndianOil Easy Axis Bank Credit Card
Related Guides & Tools
Ranked card lists IOB novio Platinum Credit Card appears in, plus calculators for card debt decisions